45 yield to maturity of a zero coupon bond
Return of zero coupon bond. Yield to Maturity of zero coupon bond Learn how to calculate effective annual rate of zero coupon bond using formula approach. @RK varsity Zero Coupon Bond Calculator 【Yield & Formula】 - Nerd Counter For instance, the maturity period of a zero-coupon bond is 10-years, its par value is $1000, the interest rate is 5.00%. When we are calculating the bond price in Excel, suppose we use the B column of the excel sheet for entering the values where B2 is the face value, B3 is the maturity time period, B4 is the interest rate.
Zero Coupon Bond Value - Formula (with Calculator) - finance formulas A 5 year zero coupon bond is issued with a face value of $100 and a rate of 6%. Looking at the formula, $100 would be F, 6% would be r, and t would be 5 years. After solving the equation, the original price or value would be $74.73. After 5 years, the bond could then be redeemed for the $100 face value.
Yield to maturity of a zero coupon bond
Spot, Yield, Par and Forward Curves | CFA Level 1 - AnalystPrep Spot Curve, Yield Curve on Coupon Bonds, Par Curve, and Forward Curve. 27 Sep 2019. Yields-to-maturity for zero-coupon government bonds could be analyzed for a full range of maturities called the government bond spot curve (or zero curve). Government spot rates are assumed to be risk-free. How to Calculate a Zero Coupon Bond Price - Double Entry Bookkeeping As the face value paid at the maturity date remains the same (1,000), the price investors are willing to pay to buy the zero coupon bonds must fall from 816 to 751, in order from the return to increase from 7% to 10%. Bond Price and Term to Maturity The longer the term the zero coupon bond is issued for the lower the bond price will be. Understanding Coupon Rate and Yield to Maturity of Bonds Here's a sample computation for a Retail Treasury Bond issued by the Bureau of Treasury: Security Name. Coupon Rate. Maturity Date. RTB 03-11. 2.375%. 3/9/2024. The Coupon Rate is the interest rate that the bond pays annually, gross of applicable taxes. The frequency of payment depends on the type of fixed income security.
Yield to maturity of a zero coupon bond. Zero Coupon Bond Value Calculator: Calculate Price, Yield to Maturity ... Calculating Yield to Maturity on a Zero-coupon Bond YTM = (M/P) 1/n - 1 variable definitions: YTM = yield to maturity, as a decimal (multiply it by 100 to convert it to percent) M = maturity value P = price n = years until maturity Let's say a zero coupon bond is issued for $500 and will pay $1,000 at maturity in 30 years. Yield Curves for Zero-Coupon Bonds - Bank of Canada These files contain daily yields curves for zero-coupon bonds, generated using pricing data for Government of Canada bonds and treasury bills. Each row is a single zero-coupon yield curve, with terms to maturity ranging from 0.25 years (column 1) to 30.00 years (column 120). The data are expressed as decimals (e.g. 0.0500 = 5.00% yield). A ... FINANCE - Module 7 Flashcards | Quizlet The yield to maturity for a zero-coupon bond is the return you will earn as an investor from holding the bond to maturity and receiving the promised face value payment. D. When prices are quoted in the bond market, they are conventionally quoted assuming the face value is $1000. E. Because we can convert any bond price into a yield, and vice ... Zero Coupon Bond - (Definition, Formula, Examples, Calculations) Cube Bank intends to subscribe to a 10-year this Bond having a face value of $1000 per bond. The Yield to Maturity is given as 8%. Accordingly, Zero-Coupon Bond Value = [$1000/ (1+0.08)^10] = $463.19 Thus, the Present Value of Zero Coupon Bond with a Yield to maturity of 8% and maturing in 10 years is $463.19.
Zero Coupon Bond | Investor.gov The maturity dates on zero coupon bonds are usually long-term—many don't mature for ten, fifteen, or more years. These long-term maturity dates allow an investor to plan for a long-range goal, such as paying for a child's college education. With the deep discount, an investor can put up a small amount of money that can grow over many years. Bonds Flashcards | Quizlet A zero-coupon bond has a yield to maturity of 9% and a par value of $1,000. If the bond matures in eight years, the bond should sell for a price of _____ today. ... a 15-year zero-coupon bond that has a par value of $1,000, and a required return of 8% would be priced at approximately A. $308. B. $315. C. $464. D. $555. E. None of the options Value and Yield of a Zero-Coupon Bond | Formula & Example - XPLAIND.com The bonds were issued at a yield of 7.18%. The forecasted yield on the bonds as at 31 December 20X3 is 6.8%. Find the value of the zero-coupon bond as at 31 December 2013 and Andrews expected income for the financial year 20X3 from the bonds. Value (31 Dec 20X3) =. $1,000. = $553.17. (1 + 6.8%) 9. Value of Total Holding = 100 × $553.17 ... Zero Coupon Bond Yield - Formula (with Calculator) - finance formulas The formula for calculating the effective yield on a discount bond, or zero coupon bond, can be found by rearranging the present value of a zero coupon bond formula: This formula can be written as This formula will then become By subtracting 1 from the both sides, the result would be the formula shown at the top of the page. Return to Top
Understanding Coupon Rate and Yield to Maturity of Bonds Here's a sample computation for a Retail Treasury Bond issued by the Bureau of Treasury: Security Name. Coupon Rate. Maturity Date. RTB 03-11. 2.375%. 3/9/2024. The Coupon Rate is the interest rate that the bond pays annually, gross of applicable taxes. The frequency of payment depends on the type of fixed income security. How to Calculate a Zero Coupon Bond Price - Double Entry Bookkeeping As the face value paid at the maturity date remains the same (1,000), the price investors are willing to pay to buy the zero coupon bonds must fall from 816 to 751, in order from the return to increase from 7% to 10%. Bond Price and Term to Maturity The longer the term the zero coupon bond is issued for the lower the bond price will be. Spot, Yield, Par and Forward Curves | CFA Level 1 - AnalystPrep Spot Curve, Yield Curve on Coupon Bonds, Par Curve, and Forward Curve. 27 Sep 2019. Yields-to-maturity for zero-coupon government bonds could be analyzed for a full range of maturities called the government bond spot curve (or zero curve). Government spot rates are assumed to be risk-free.
Learn to Calculate Yield to Maturity in MS Excel

Zero-Coupon Bonds: Characteristics and Examples
Modified Duration - Zero Coupon Bond Modified Duration ...
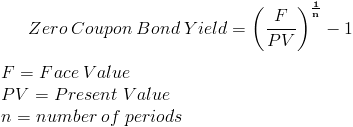
Zero Coupon Bond Yield - Formula (with Calculator)
Yield to Maturity
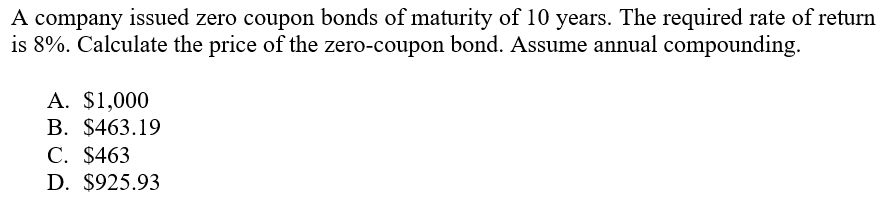
Answered: A company issued zero coupon bonds of… | bartleby
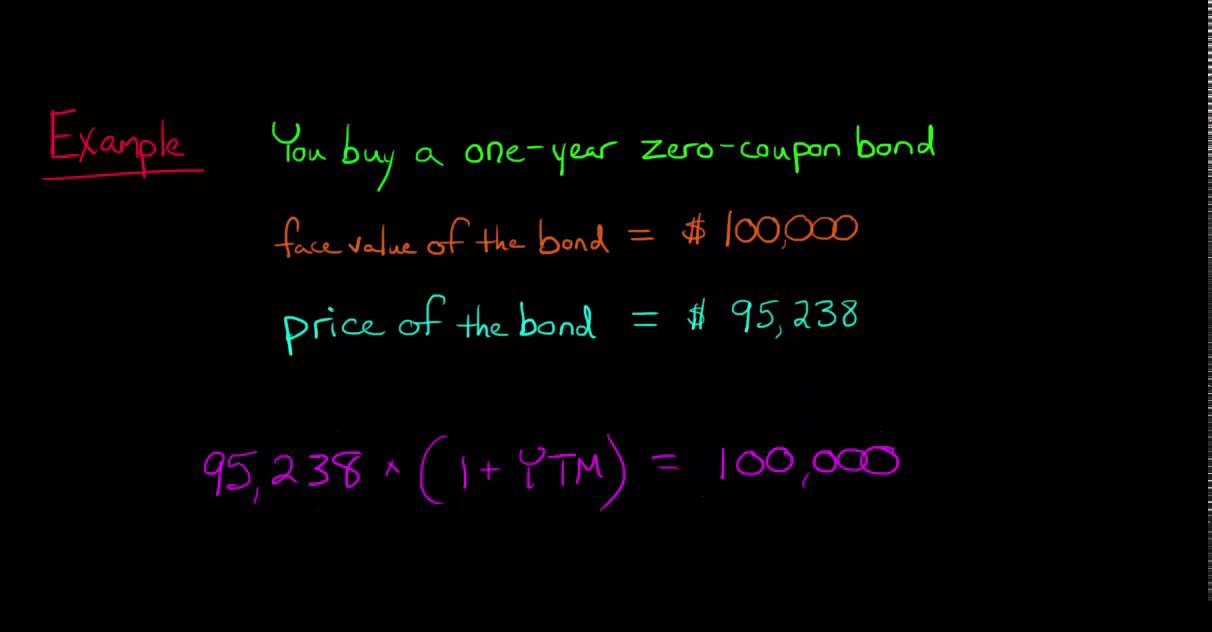
Calculating the Yield of a Zero Coupon Bond

MGT338 - Chapter 6: Valuing Bonds | Team Study
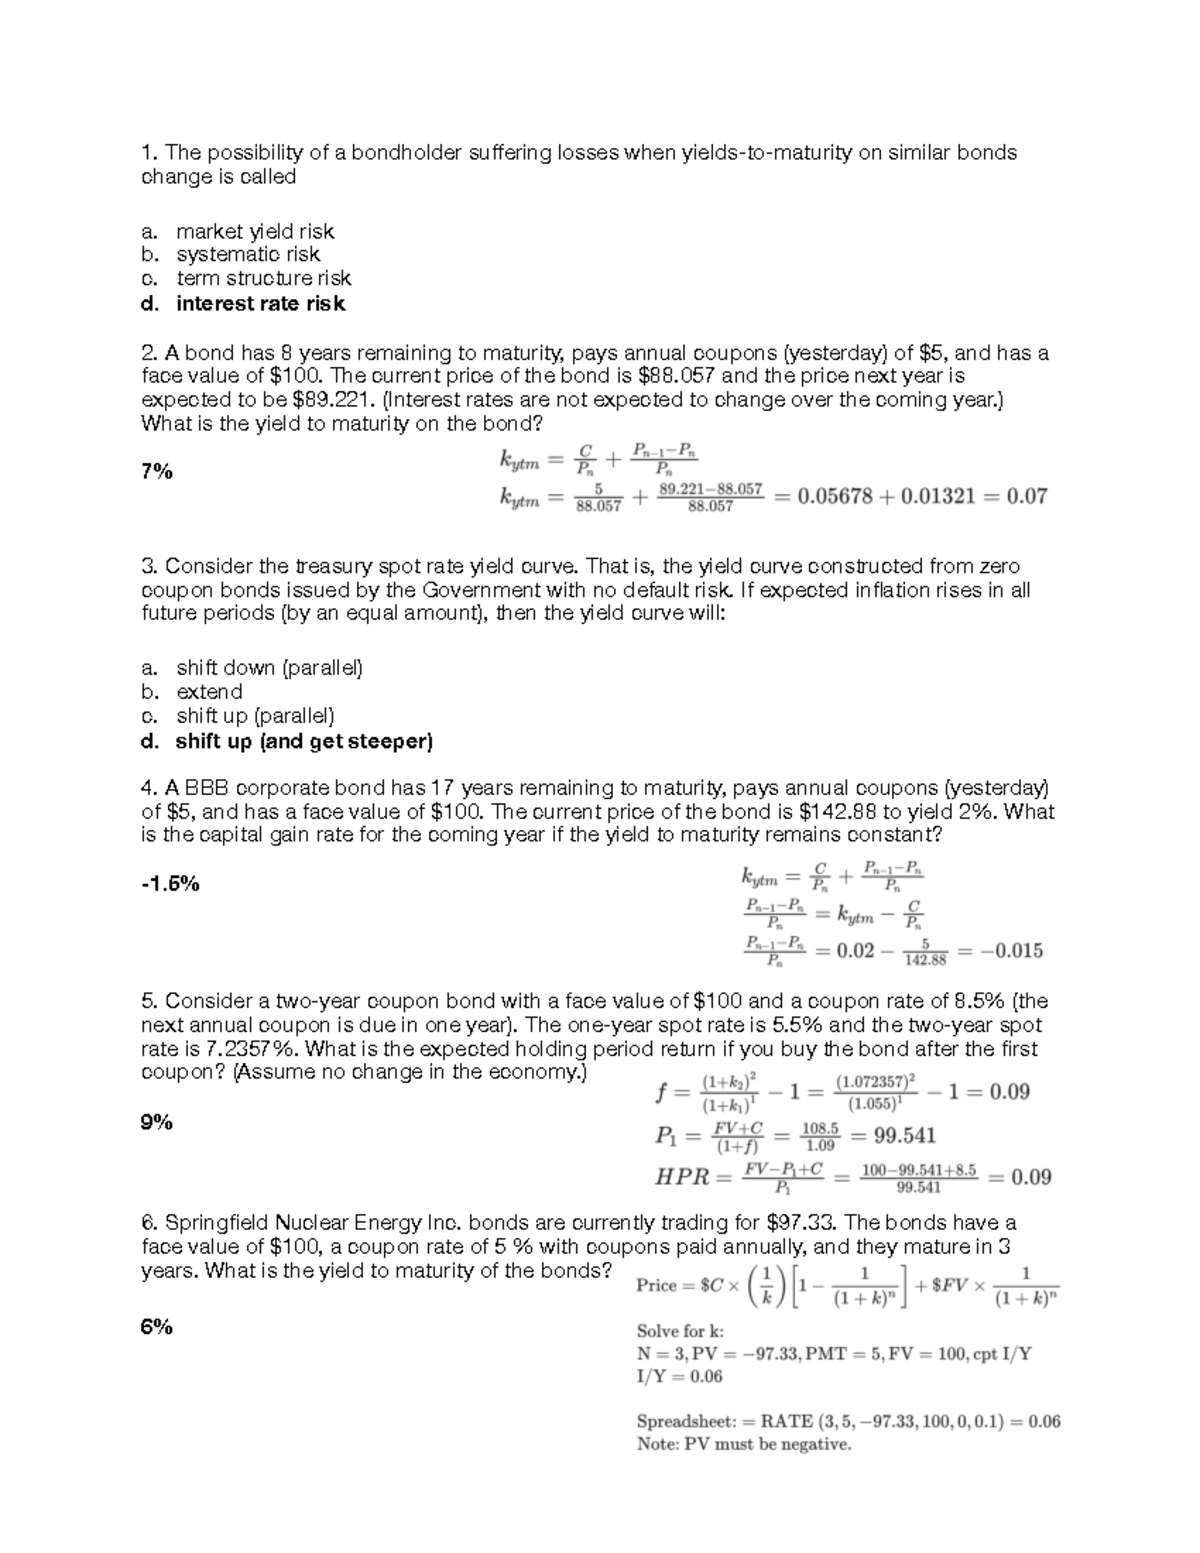
Chapter 7, interest rates and bonds - The possibility of a ...

The yield to maturity (YTM) on 1-year zero-coupon bonds is 5 ...

Yield to Maturity – What it is, Use, & Formula – Speck & Company

2: Value of Zero-Coupon Bond Against Yield to Maturity ...
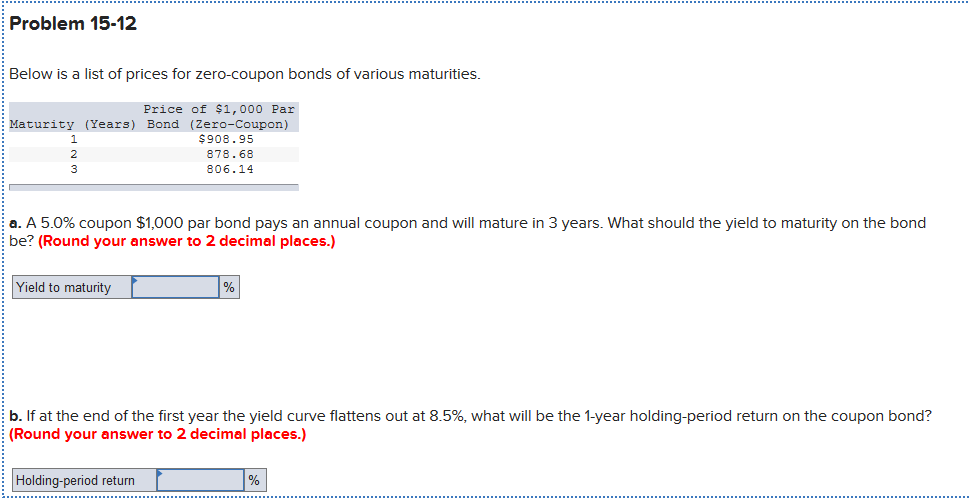
Answered: Below is a list of prices for… | bartleby

YTM: Formula and Calculator (Step-by-Step)
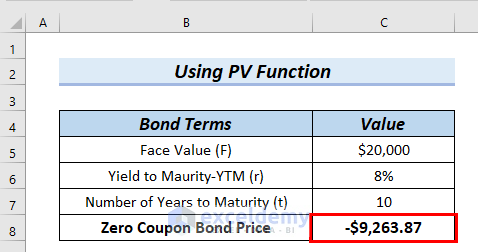
Zero Coupon Bond Price Calculator Excel (5 Suitable Examples)
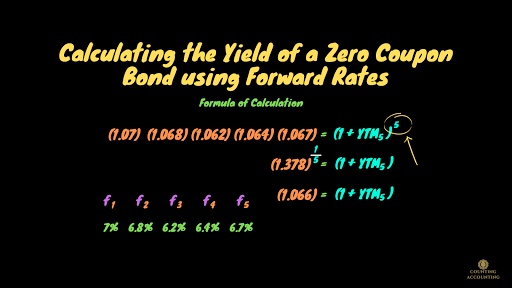
How to Calculate the Yield of a Zero Coupon Bond Using ...
Interest Rates and Bond Valuation

A newly issued 20-year maturity, zero-coupon bond is issued ...
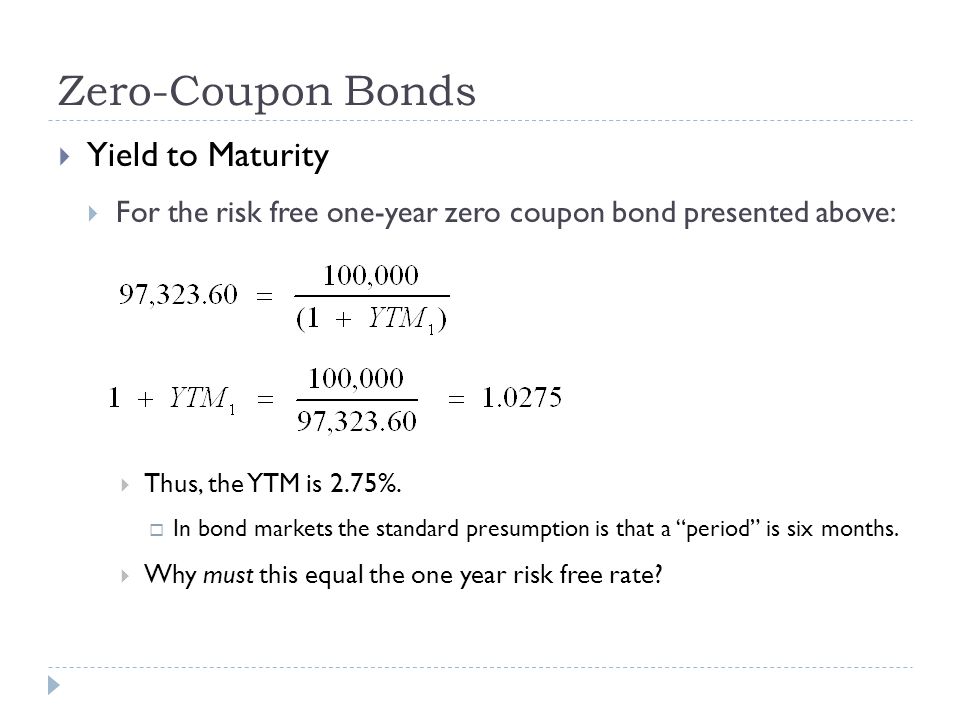
Valuing Securities Stocks and Bonds. - ppt video online download

Solved The yield to maturity on 1-year zero-coupon bonds is ...
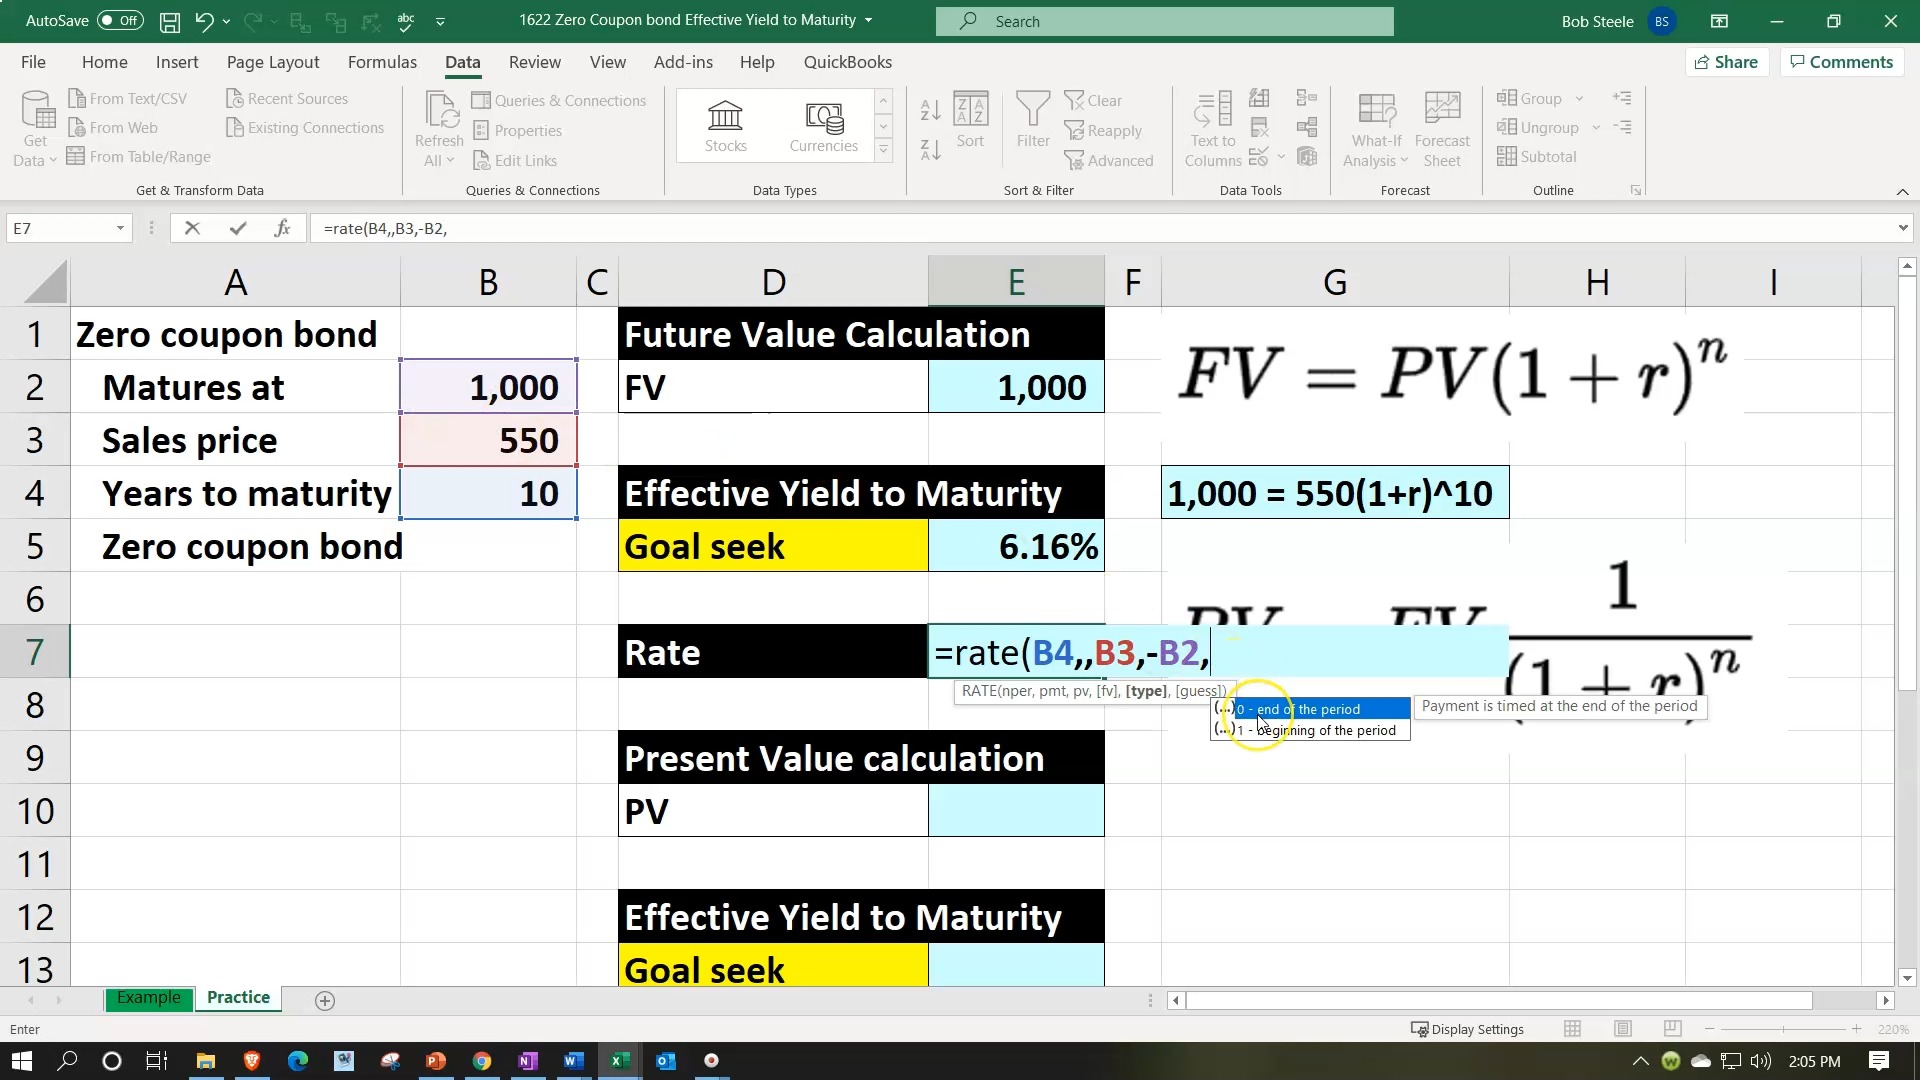
Zero Coupon bond Effective Yield to Maturity 1622 | Facebook

Understanding Interest Rates - ppt download
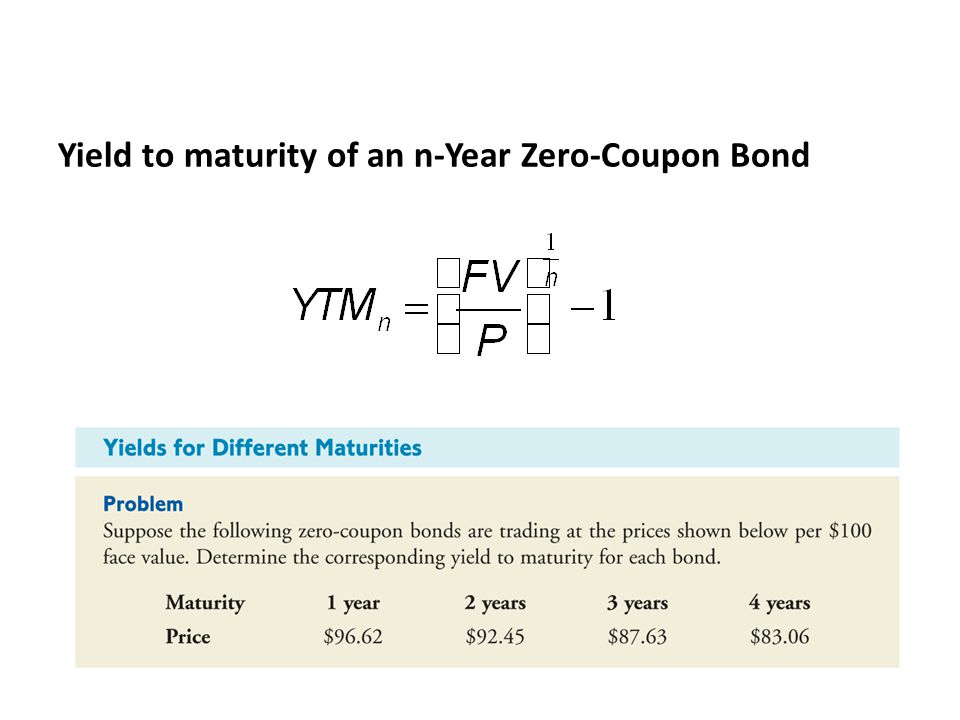
Bond Valuation Chapter ppt video online download
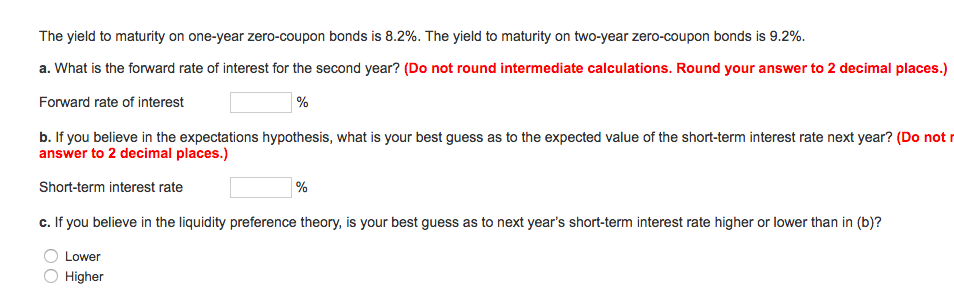
Solved The yield to maturity on one-year zero-coupon bonds ...
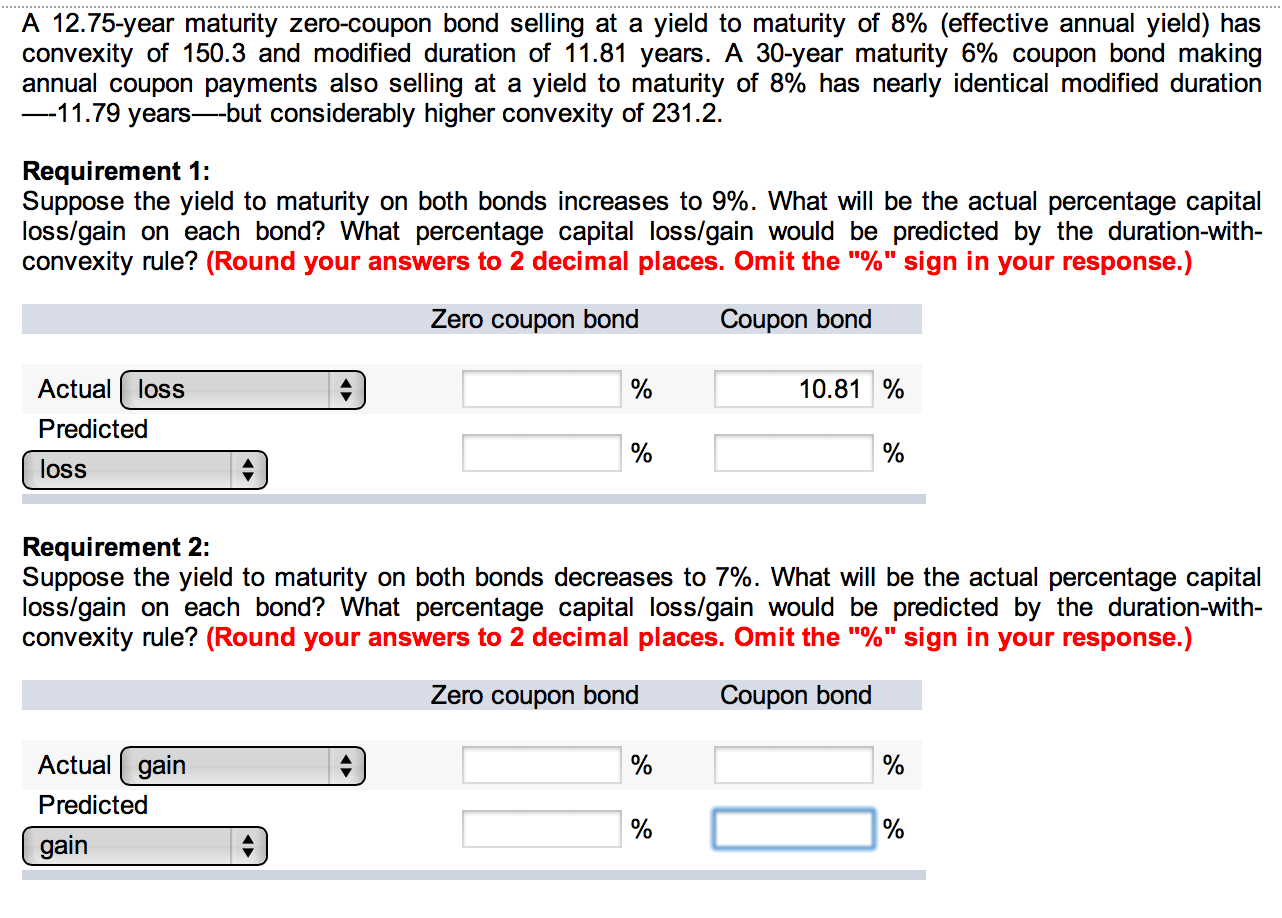
A 12.75-year maturity zero-coupon bond selling at a | Chegg.com

PDF) Online Test 1 Answer Key | àOKF KDF - Academia.edu
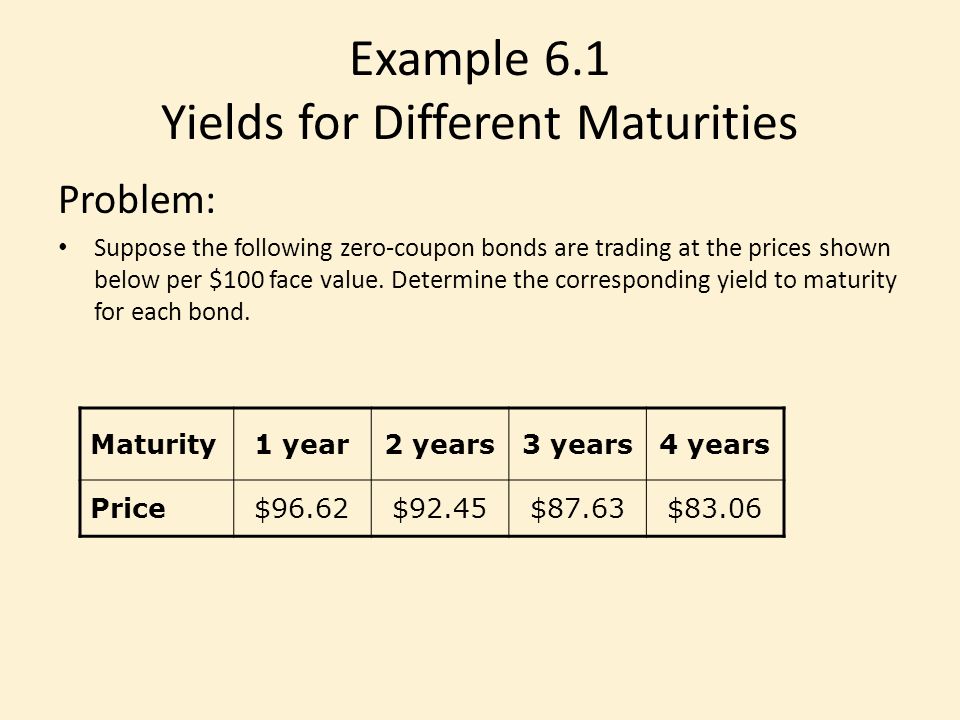
Chapter 6 Bonds 6-1. Chapter Outline 6.1 Bond Terminology 6.2 ...
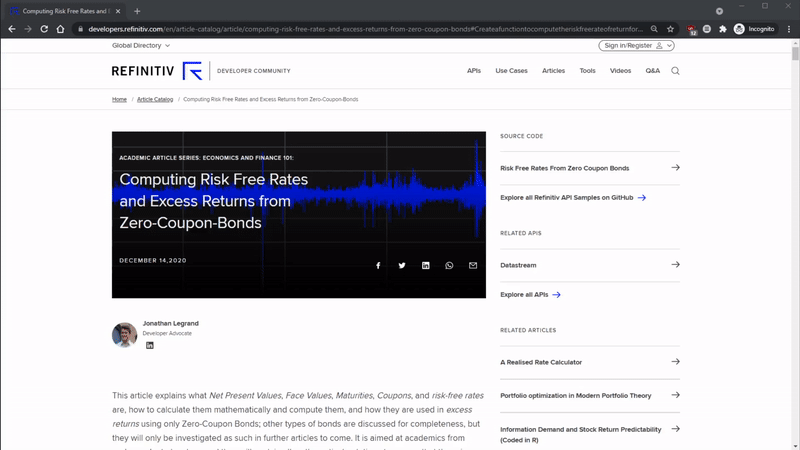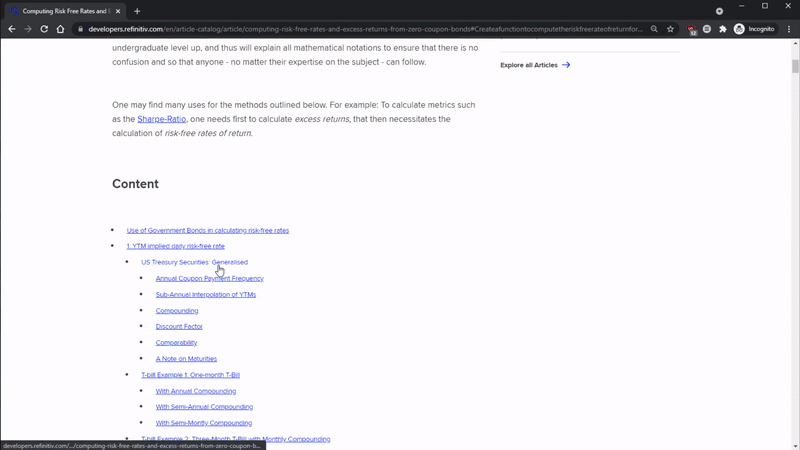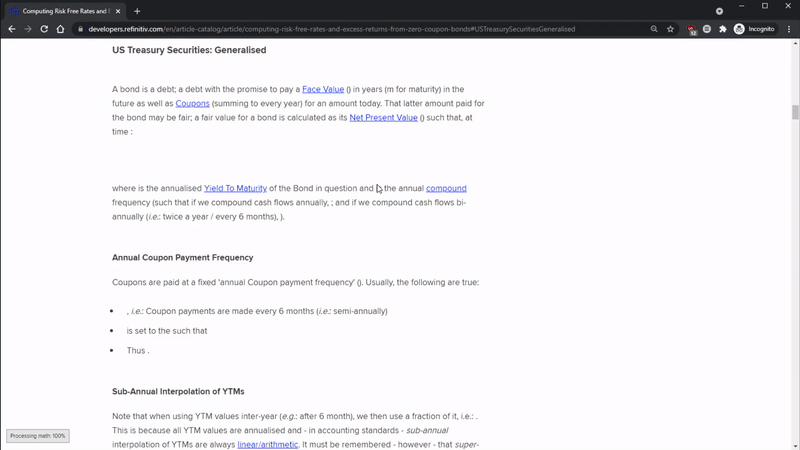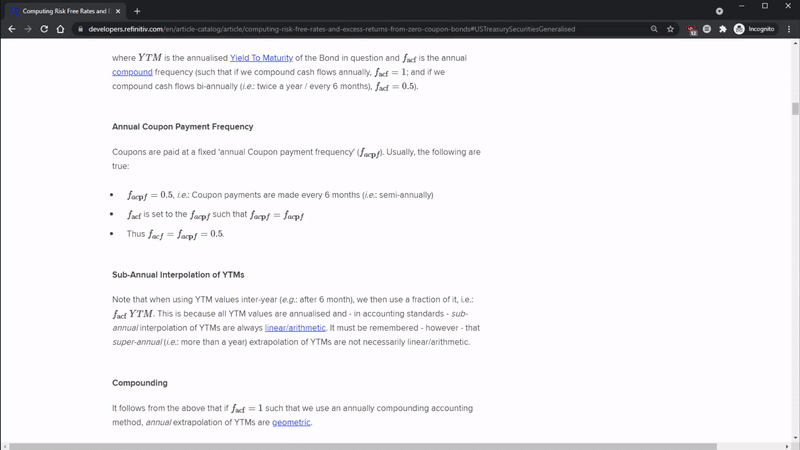
Computing Risk Free Rates and Excess Returns Part 1: From ...
Explain conceptually how bonds are priced. Moreover, define ...
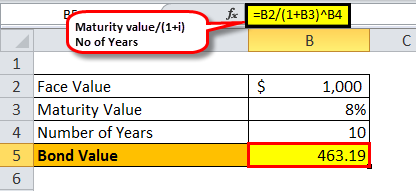
Zero Coupon Bond - (Definition, Formula, Examples, Calculations)
Chapter 1
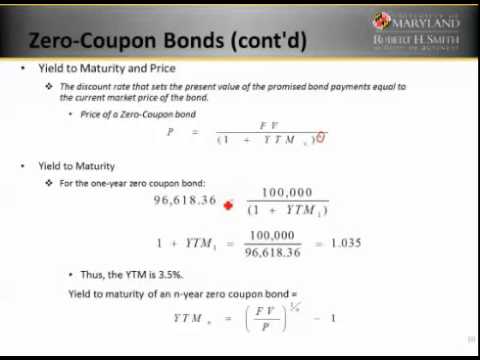
Finding YTM of a Zero Coupon Bond (6.2.1)

A newly issued 20-year maturity, zero-coupon bond making ...
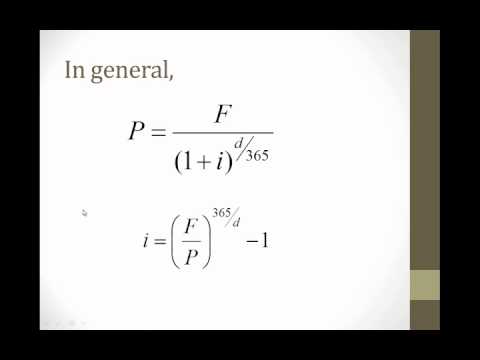
Zero Coupon Bonds
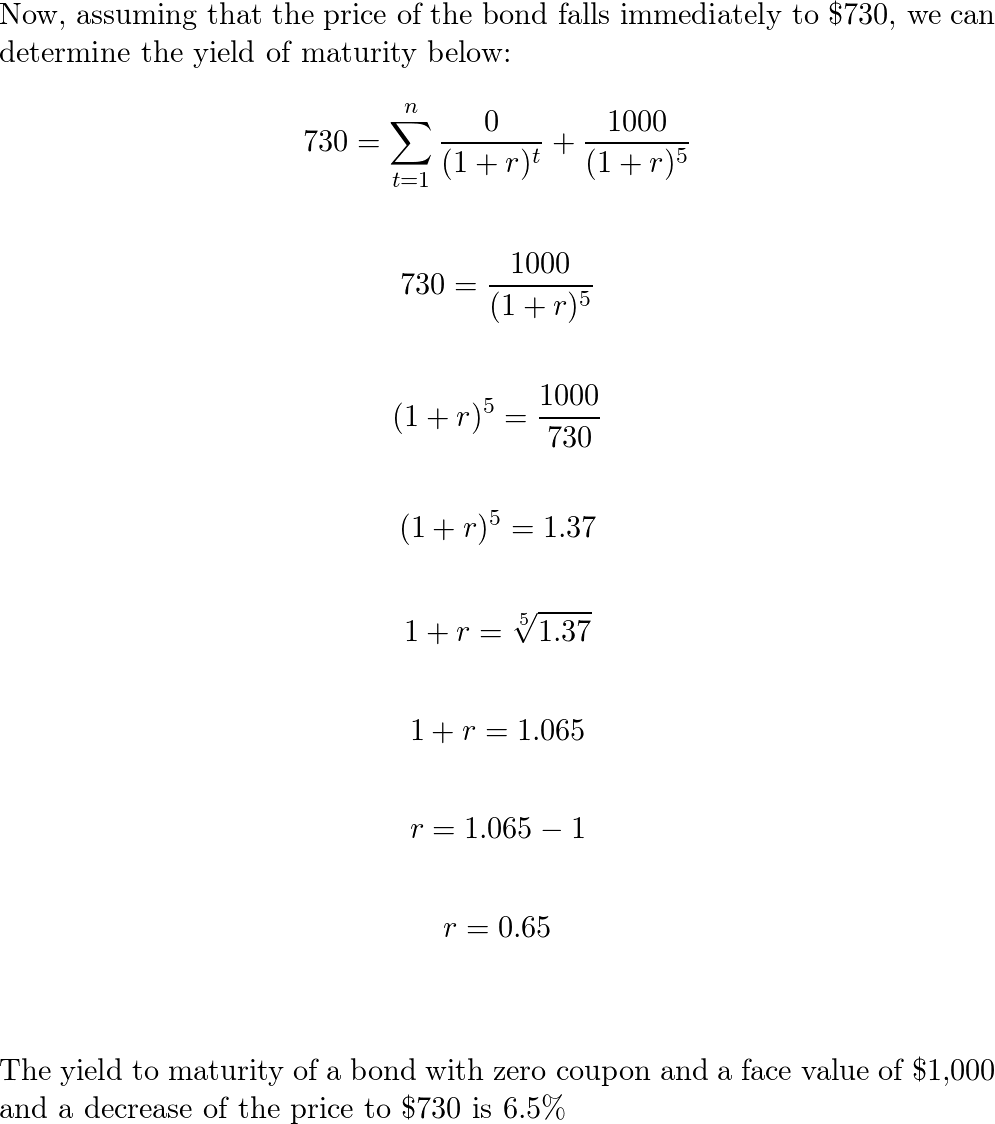
A zero-coupon bond with face value $1,000 and maturity of fi ...
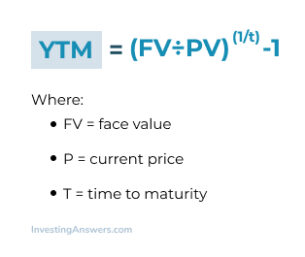
Yield to Maturity (YTM) Definition & Example | InvestingAnswers
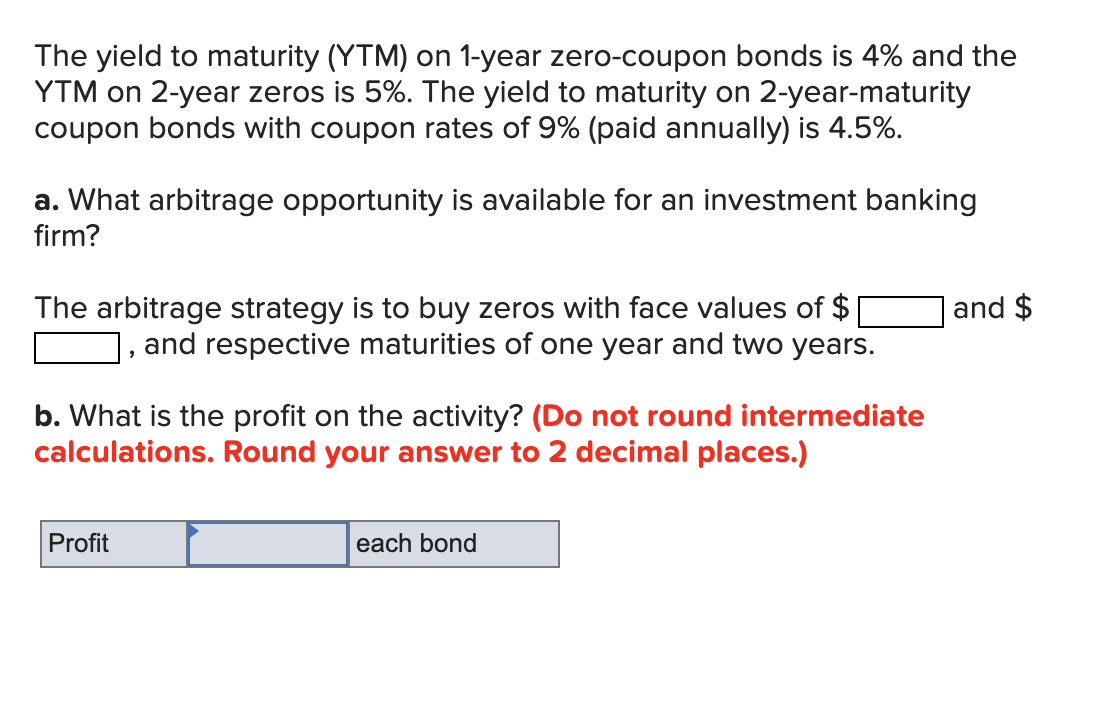
Solved The yield to maturity (YTM) on 1-year zero-coupon ...

Zero Coupon Bonds Explained (With Examples) - Fervent ...
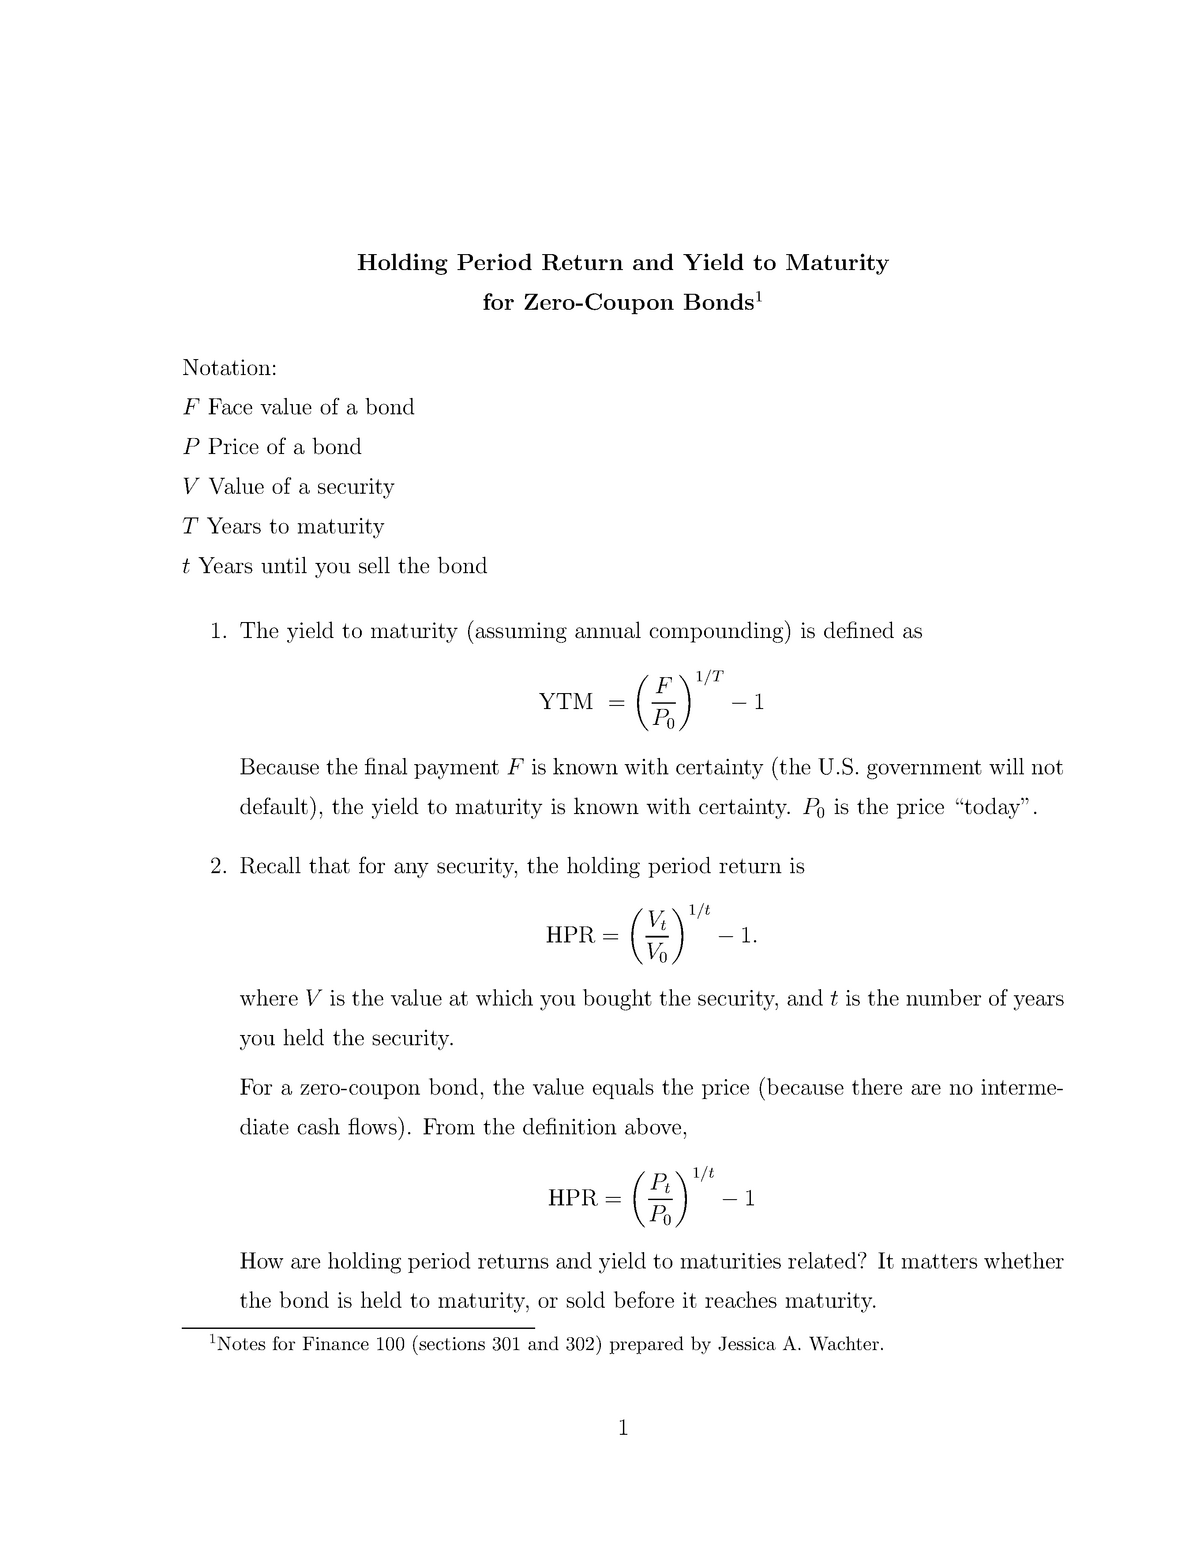
Holding Period Return and Yield to Maturity for Zero-Coupon ...
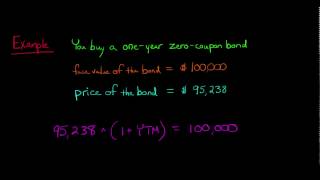
Calculating the Yield of a Zero Coupon Bond

Zero-Coupon Bond - an overview | ScienceDirect Topics
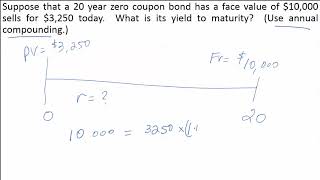
Calculate the YTM of a Zero Coupon Bond - YouTube

Understanding Interest Rates - ppt download
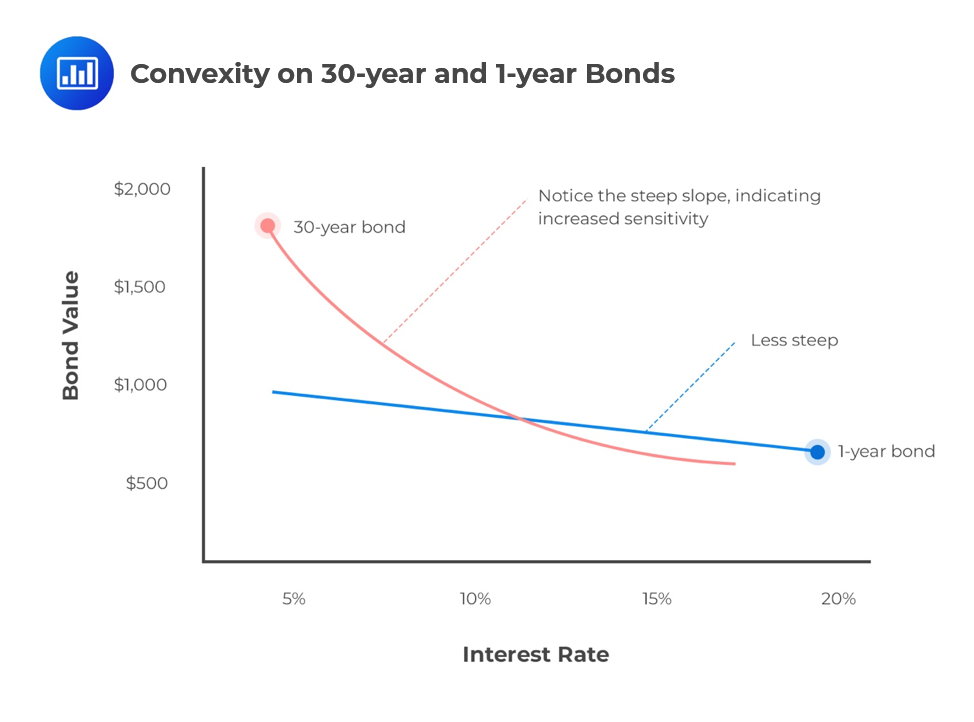
Bond's Maturity, Coupon, and Yield Level | CFA Level 1 ...
Zero Coupon Bond Calculator - Calculator Academy
Post a Comment for "45 yield to maturity of a zero coupon bond"